Is Your Tax Dollar Funding Public Services or Government Debt?
Is Your Tax Dollar Funding Public Services or Government Debt?
Canada’s rising debt-interest costs raise an important question: how much of the money Canadians pay in taxes goes toward public services, and how much goes toward servicing the national debt?
Every year, Canadians pay taxes to support healthcare, retirement benefits, infrastructure, education, public safety and other government programs. These services play an important role in the country’s economy and the daily lives of its citizens.
However, government spending has another cost that receives less attention: interest on public debt. When governments borrow money, they must repay the principal and pay interest to lenders. This creates a long-term financial obligation that can affect future budgets.
The issue is not simply whether Canada should borrow money. The more important question is whether government borrowing delivers enough long-term value to justify its cost.
Canada’s $53.4 Billion Debt-Interest Bill
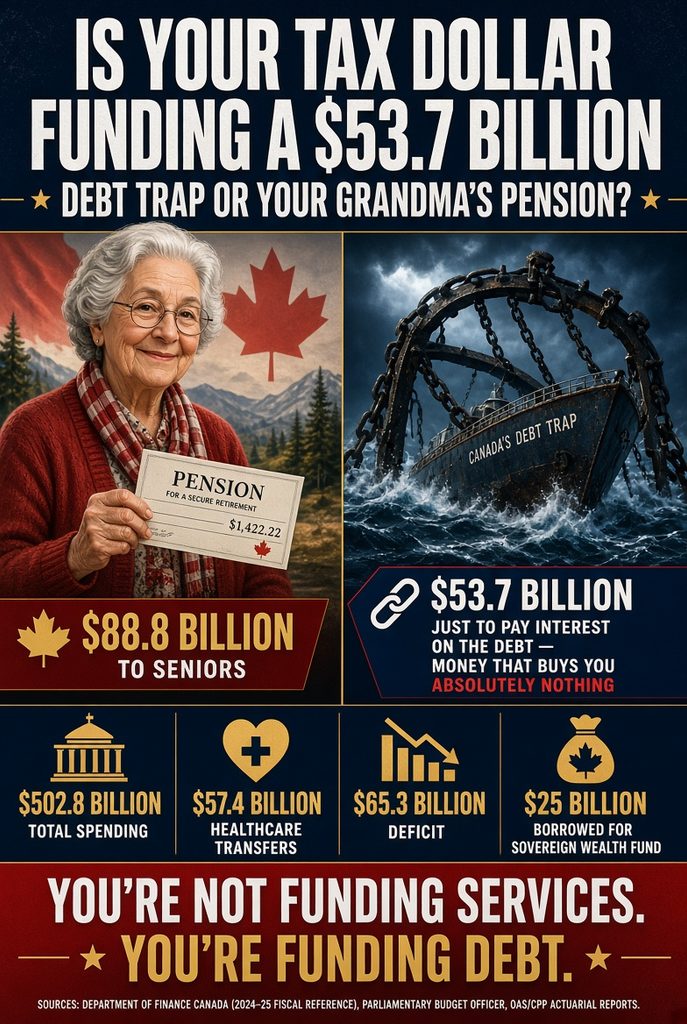
According to the Government of Canada’s Annual Financial Report for the 2024–2025 fiscal year, federal public debt charges reached approximately $53.4 billion. These charges accounted for about 9.8% of total federal expenses of $547.3 billion.
In practical terms, the federal government spent almost $1 out of every $10 in reported expenses on public debt charges. This money covered interest costs rather than directly funding new healthcare services, retirement payments or infrastructure projects.
Debt interest is a real and recurring expense. However, it is important to understand that borrowing can also finance investments, support the economy during a crisis or fund infrastructure that benefits Canadians for decades.
The key issue is whether the benefits of borrowing outweigh the cost of servicing the debt.
Source: Government of Canada, Annual Financial Report 2024–2025.
How Much Does Canada Spend on Public Services?
Federal spending supports a wide range of programs. These include financial assistance for seniors, transfers to provincial governments, employment insurance, child benefits and government operations.
For the 2024–2025 fiscal year, the federal government reported:
- $547.3 billion in total expenses.
- $53.4 billion in public debt charges.
- $80.3 billion in elderly benefits.
- $105.1 billion in transfers to other levels of government.
These figures show that the federal budget supports both public services and financial obligations created by past borrowing.
It is also important to distinguish between federal spending and total public spending in Canada. Provinces and territories manage many healthcare and education services. Federal transfers help support these responsibilities, but the federal government does not directly control every service funded by those transfers.
The figures above are federal amounts. They do not represent all spending by every level of government.
The Difference Between a Deficit and Debt
These two terms are often used together, but they mean different things.
A budget deficit occurs when government expenses exceed government revenues during a fiscal year.
Government debt is the accumulated financial obligation that results from borrowing and other financial transactions over time.
For example, if a government collects $500 billion in revenue but spends $536 billion, it has a deficit of $36 billion. It must finance that gap through borrowing or other financing measures.
The government then has to pay interest on its outstanding debt.
Canada recorded a federal budget deficit of $36.3 billion in 2024–2025. This was lower than the $61.9 billion deficit recorded in 2023–2024. However, the country still ended the year with a deficit.
This distinction matters. A smaller deficit does not mean the government has eliminated its debt. It means the annual gap between revenue and expenses has narrowed.
Source: Government of Canada, Annual Financial Report 2024–2025.
Why Rising Interest Costs Matter to Canadians
Interest payments compete with other demands on public funds. When debt charges increase, governments have fewer resources available for new spending unless they raise revenue, reduce other expenses or borrow more.
This creates several potential risks.
1. Less Room for Future Spending
Governments face competing demands for healthcare, housing, infrastructure, public safety and social programs.
As interest costs rise, it becomes harder to fund new priorities without making difficult budget decisions.
2. Greater Exposure to Interest Rates
Government borrowing costs depend on several factors, including interest rates, the amount of debt that must be refinanced and investor demand for government securities.
Higher borrowing costs can increase the expense of issuing new debt and refinancing maturing obligations.
3. Greater Pressure on Future Taxpayers
Government debt can spread the cost of an investment across generations. This can be reasonable when future generations also benefit from the investment.
However, borrowing to finance ongoing expenses without a sustainable plan can leave future taxpayers responsible for costs that provide little lasting benefit.
4. Difficult Choices During Economic Downturns
A government with substantial debt-service obligations may have less flexibility to respond to a recession, a public emergency or an unexpected economic shock.
This does not mean that borrowing is always harmful. It means that the amount, purpose and cost of borrowing matter.
Is All Government Borrowing Bad?
No. Treating every dollar of government borrowing as waste would be just as misleading as assuming every government expense provides good value.
Borrowing can make sense when it finances productive infrastructure, improves economic capacity or helps manage an extraordinary crisis.
For example, a well-planned transportation project may reduce travel times, support businesses and improve access to employment for many years.
By contrast, borrowing to cover recurring expenses without a credible plan to balance future budgets can create a different problem. The government receives the immediate benefit of spending while taxpayers face the ongoing cost of debt.
A responsible assessment should examine three questions:
- What does the borrowing finance?
- What measurable economic or social benefits does it deliver?
- Can the government service its debt without placing excessive pressure on future budgets?
These questions provide a more useful test than simply looking at the size of the debt.
What About Canada’s Spending on Seniors and Healthcare?
Retirement benefits and healthcare transfers are major parts of federal spending. They should not be treated as money wasted simply because they are large budget items.
Old Age Security and related elderly benefits provide financial support to eligible seniors. Federal healthcare transfers help provinces and territories finance healthcare systems.
These programs serve real needs. At the same time, governments must manage their costs alongside debt interest and other spending commitments.
Canada’s 2024–2025 federal accounts reported approximately $80.3 billion in elderly benefits and $105.1 billion in transfers to other levels of government.
The policy challenge is to maintain essential programs while keeping public finances sustainable.
This requires clear reporting, realistic forecasts and regular reviews of whether government programs achieve their intended results.
What Should Canadians Watch in Future Federal Budgets?
The size of the deficit is only one measure of fiscal performance. Canadians should also examine several other indicators.
Debt charges: Are interest costs rising faster than federal revenue?
Debt relative to the economy: Is the government’s debt becoming more difficult to support relative to Canada’s economic output?
Program results: Are large public expenditures producing measurable improvements in healthcare, housing, productivity and other priorities?
Borrowing purpose: Is new borrowing financing long-term investments or mainly covering recurring expenses?
Fiscal forecasts: Do government projections account for realistic economic growth, interest rates and future spending pressures?
These indicators help distinguish between borrowing that may strengthen the economy and borrowing that could restrict future choices.
The Bottom Line: Every Dollar Has an Opportunity Cost
Canada’s federal budget must balance immediate public needs with long-term financial responsibility.
The government must fund essential services. It must also manage the cost of past borrowing. Neither responsibility can be ignored.
The $53.4 billion spent on federal public debt charges in 2024–2025 demonstrates why debt management deserves public attention. That figure does not mean Canadians received no value from government spending. It means that servicing existing financial obligations consumed a significant share of the federal budget.
The central question is not whether Canada should spend money. It is whether Canadians receive sufficient value from that spending, whether borrowing remains sustainable and whether future governments will retain enough financial flexibility to meet the country’s needs.
Taxpayers deserve clear answers about both sides of the ledger: what their money funds today and what financial obligations it creates for tomorrow.
Sources: Government of Canada, Annual Financial Report 2024–2025; Department of Finance Canada, Debt Management Report 2024–2025.